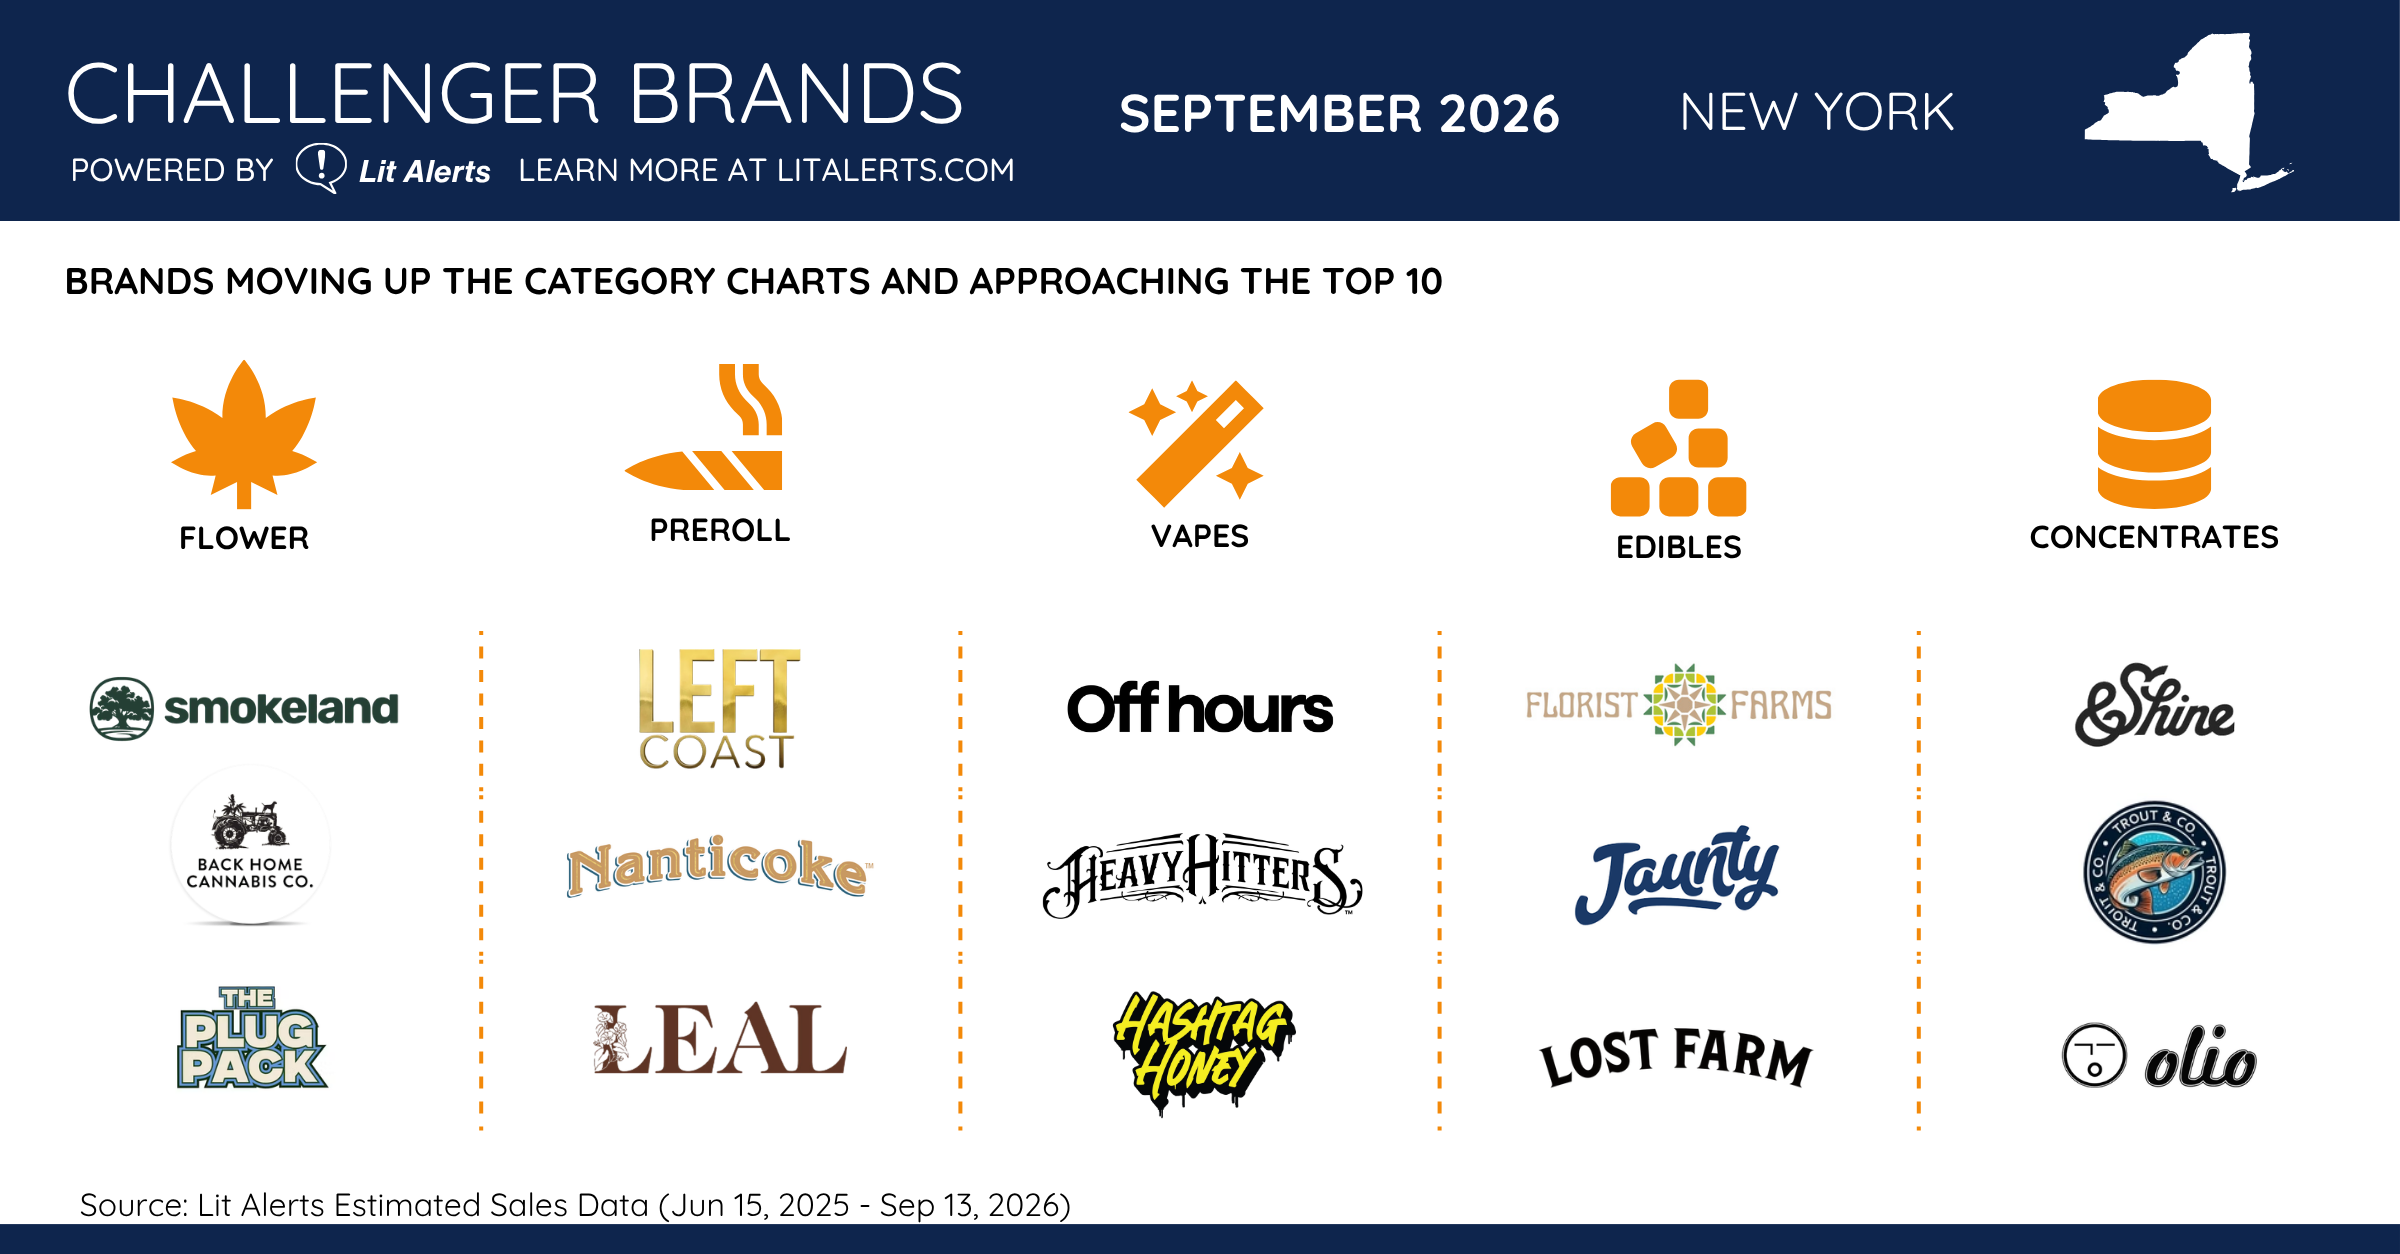
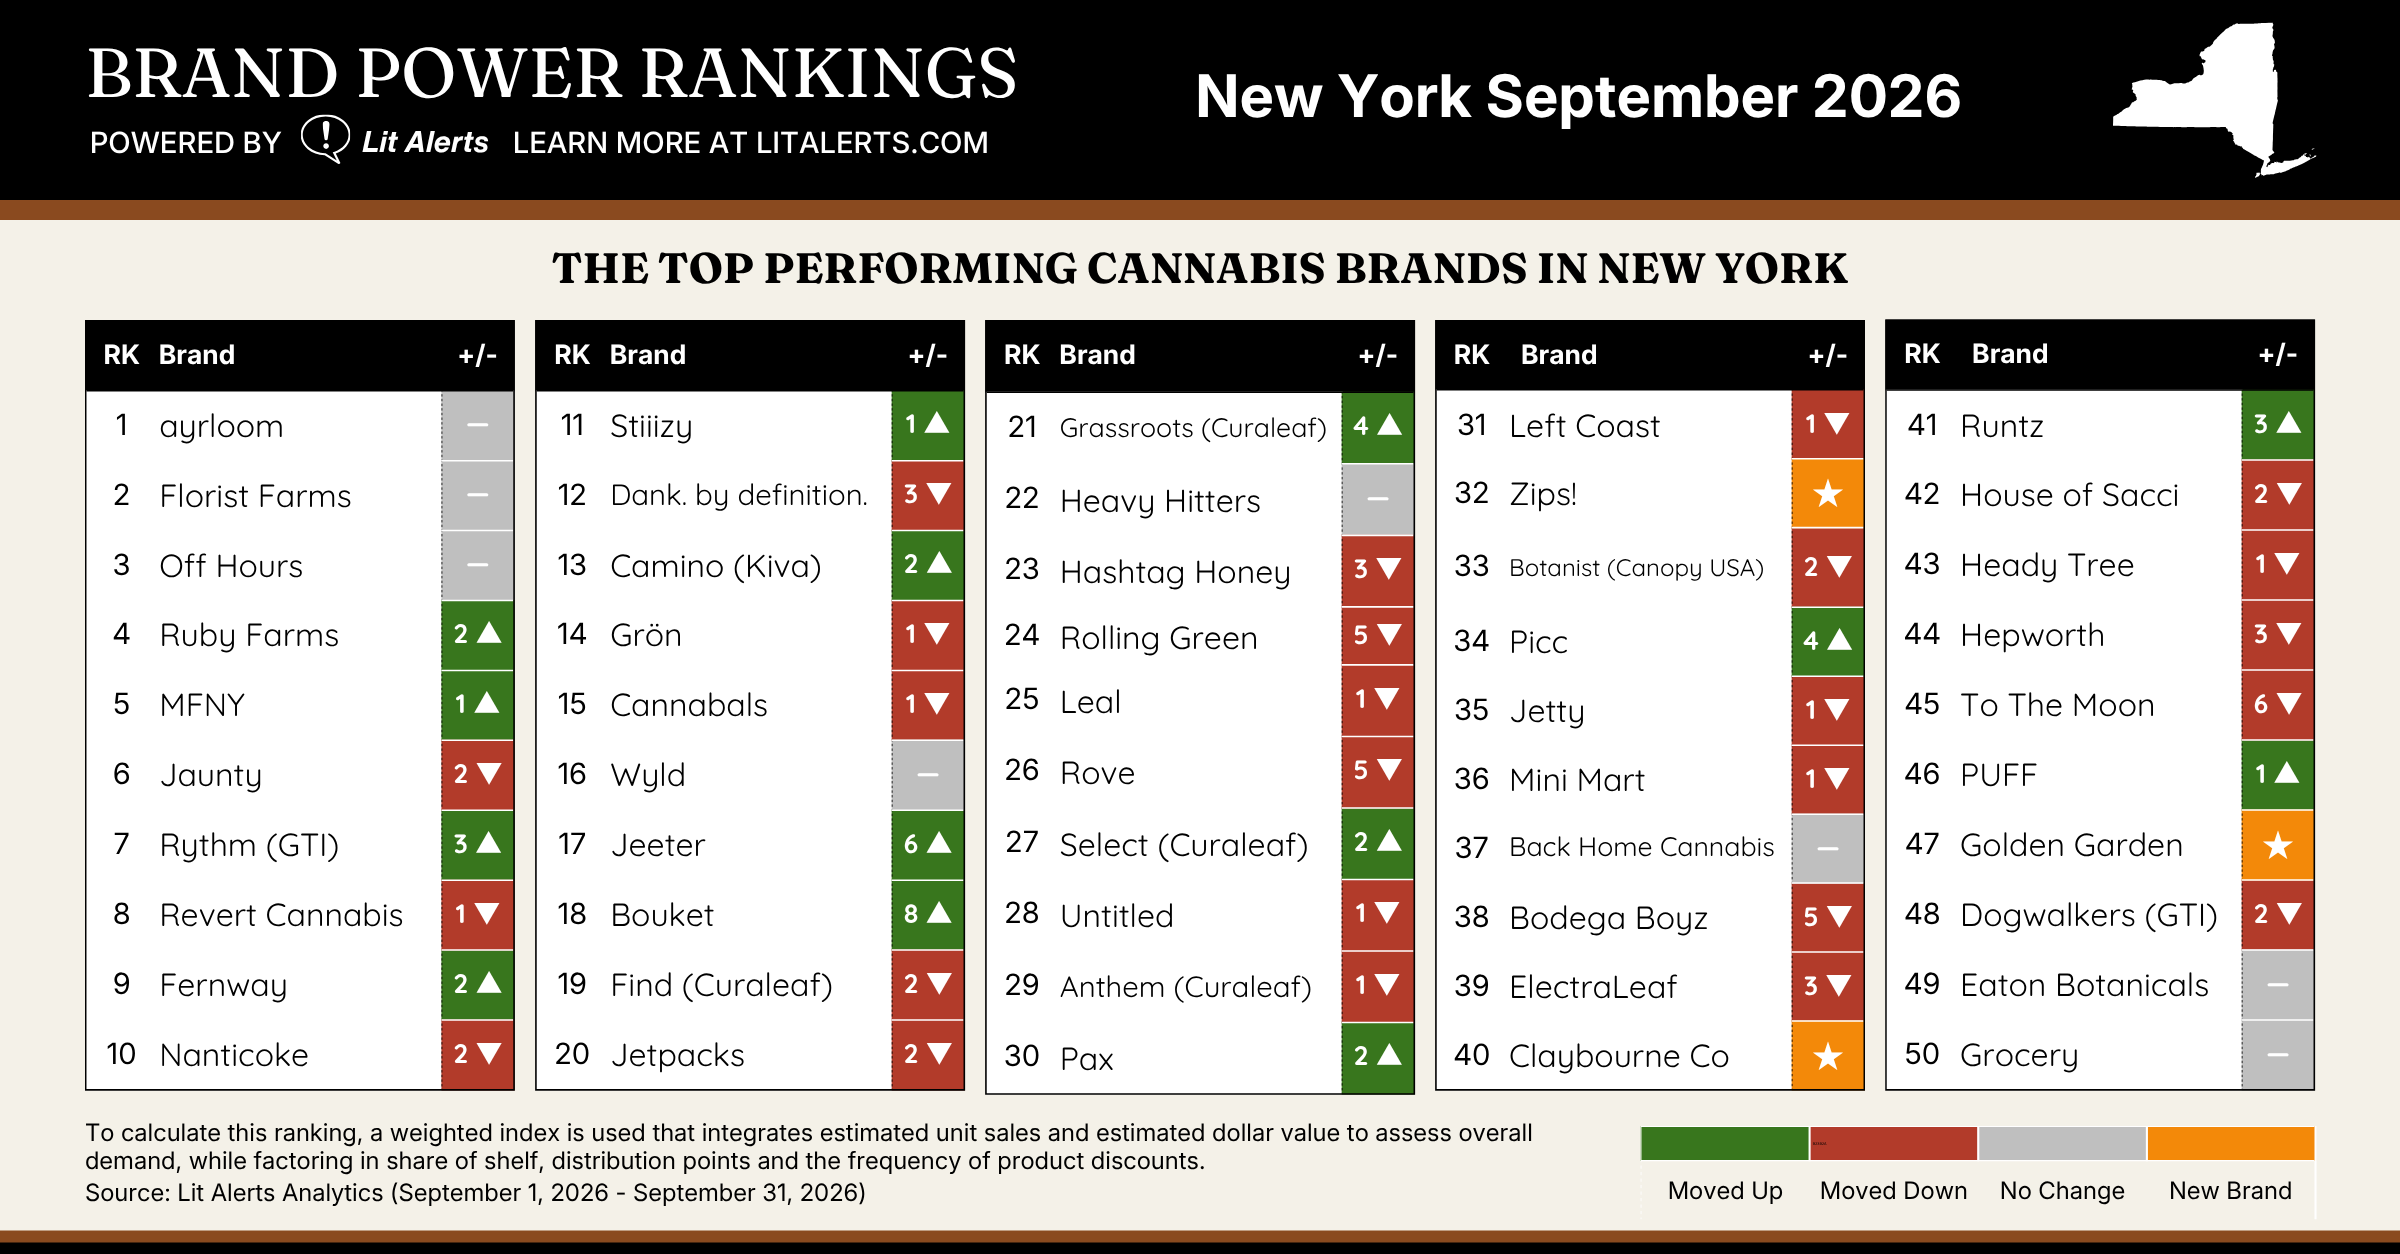
New York’s adult-use cannabis market experienced a decisive structural shift in September 2026, breaking away from summertime equilibrium and introducing significant velocity across the Top 50 leaderboard. While the top three podium spots remain firmly anchored by early-market champions, the surrounding landscape underwent substantial repositioning as national powerhouses accelerated their East Coast campaigns and aggressive new entrants disrupted established distribution channels. The September Lit Alerts Brand Power Rankings, calculated using a weighted index integrating unit sales, gross dollar value, active door counts, shelf share, and discounting frequency, confirms that static shelf presence is no longer guaranteed for early entrants.
Executive Market Dynamics: Stability at the Apex, Turbulence Below
Comparing September 2026 performance against August, July, and June reveals a striking contrast in market behavior. August was defined by structural rigidness at the top, where positions one through six did not move a single spot from July. September upended that stagnation. Seven of the top ten positions changed hands this month, signaling that retail buyers across New York are actively auditing menu performance and reallocating shelf space to reward high-velocity brands.
Despite turbulence across the upper tier, the market’s triumvirate at the podium remains unbroken. ayrloom (#1), Florist Farms (#2), and Off Hours (#3) held their positions with total authority. These three leaders have defended the top three spots across June, July, August, and September 2026, creating a formidable defensive wall that resists both MSO scale and national expansion. Their continued dominance stems from deep retail relationships, wide SKU breadth spanning edibles, vapes, and beverages, and consistent stock availability.
Top 10 Reshuffle & The Exit of Dank. by definition.
Below the top three podium, the battle for top-ten market share escalated dramatically throughout September. The primary highlight of this reshuffle is the departure of Dank. by definition. from the top ten rankings. After holding #7 in June and July and sliding two spots to #9 in August, Dank. by definition. fell another three positions in September to land at #12. This drop underlines mounting competitive pressure within premium flower and pre-rolls, where shifting consumer preferences punish brands experiencing velocity slowdowns.
The top ten featured extensive movement as competing operators surged forward:
Ruby Farms advanced +2 positions to claim #4, rising from #6 in July and #5 in August to reach its highest ranking of the year.
MFNY edged up +1 position to #5, continuing its steady trajectory as one of the state’s premier craft concentrate and flower producers.
Jaunty experienced a -2 drop to #6, slipping out of the top five for the first time since June as competing vape and edible lines gained ground.
Rythm (GTI) posted a major top-ten leap, advancing +3 spots to #7. Building on its August climb (+1 to #10), this surge demonstrates expanding distribution from multi-state operator Green Thumb Industries.
Revert Cannabis adjusted down -1 position to #8 after surging into the top tier during August.
Fernway staged an impressive recovery, vaulting +2 spots to #9 and re-entering the top ten after briefly dropping to #11 in August.
Nanticoke dropped -2 spots to round out the top ten at #10, down from #8 in August and #8 in July.
National Powerhouses Accelerate: Jeeter's Surge & Stiiizy's Advance
While local operators continue defending regional turf, national powerhouses with multi-state playbooks are executing systematic expansion campaigns across New York. The September data highlights two national leaders making major strides through distribution expansion and brand recognition.
Jeeter Moves Aggressively Upward
Jeeter delivered the most explosive vertical climb in the upper half of the chart, leaping +6 positions to secure #17 in September. This upward movement represents an ongoing multi-month trajectory. After holding #26 in July and advancing +3 spots to #23 in August, Jeeter’s six-spot jump in September proves that its high-potency infused pre-rolls and high-visibility retail displays are capturing significant market share. Jeeter’s climb illustrates how national players with streamlined supply chains can rapidly convert brand awareness into retail velocity.
Stiiizy Closes In on the Top 10
Secondarily, vape titan Stiiizy advanced another spot to reach #11, positioning itself directly on the doorstep of the top ten. Tracking Stiiizy over the past four months highlights consistent progress:
June 2026: #19
July 2026: #14 (+5 spots)
August 2026: #12 (+3 spots)
September 2026: #11 (+1 spot)
Stiiizy’s monthly advance reflects sustained consumer demand for its proprietary pod systems, paired with expanding distribution across newly licensed dispensaries statewide. Sitting at #11, Stiiizy is now in prime position to challenge top-ten incumbents.
New Entrants: Zips! Delivers an All-Star Debut
September welcomed three new brands to the Top 50, headlined by an extraordinary chart entry from bulk-flower challenger Zips!.
Zips! made an all-star debut, entering the rankings directly at #32. Debuting at #32 represents the highest initial entry for any new brand over recent months, far outperforming August debutants such as PUFF (#47), High Peaks (#48), and Eaton Botanicals (#49). The high entry ranking of Zips! underscores growing consumer demand for value-oriented, high-volume offerings.
Claybourne Co made its chart debut at #40 with strong initial distribution in key retail stores on Long Island.
Golden Garden entered the Top 50 at #47, providing fresh energy in the bottom tier.
These new entries demonstrate that while breaking into the top 20 requires substantial scale, buyers remain eager to add brands that address specific menu price points.
Mid-Tier Churn & Portfolio Shifts
Beyond the top tier, the middle section of the September rankings exhibited substantial vertical movement.
Notable Climbers
Bouket achieved the largest single-month jump across the entire Top 50, skyrocketing +8 spots to claim #18. This gain builds on its progress from May (#30) and August (#26), solidifying Bouket as one of the state’s fastest-growing brands.
Grassroots (Curaleaf) jumped +4 positions to reach #21, leading portfolio stabilization for Curaleaf.
Picc climbed +4 spots to #34, recovering ground after holding flat at #38 in August.
Runtz gained +3 spots to land at #41, continuing a steady upward trend.
Camino (Kiva) advanced +2 positions to #13, regaining momentum after dropping two spots in August.
Select (Curaleaf) moved up +2 positions to #27, rebounding from a five-spot slip in August.
Pax gained +2 positions to reach #30, re-entering the top 30.
Structural Takeaways for New York Cannabis Brands
Analyzing the brand power trajectory across June, July, August, and September 2026 reveals critical strategic shifts defining the Empire State’s adult-use landscape. For operators, wholesale teams, and brand strategists navigating New York’s expanding retail ecosystem, three core takeaways define current market dynamics:
Early-Mover Advantage Has Expired—Top Positions Require Active Defense
Initial wholesale distribution agreements and early retail menu placement are no longer sufficient to guarantee long-term shelf security. As licensed dispensary buyers across New York transition from rapid inventory accumulation to aggressive menu curation, slow-moving SKUs are being systematically audited and replaced. The departure of Dank. by definition. from the top ten (sliding from #7 in June down to #12 in September) alongside Jaunty’s slip to #6 demonstrate that even fan favorites face intense pressure. Protecting top-tier ranking now demands continuous account engagement, tailored budtender education, and active retail velocity management.National Playbooks Are Successfully Scaling East Coast Footprints
The sustained momentum of multi-state powerhouses confirms that national brand equity, capital depth, and standardized supply chains are successfully capturing Empire State market share. Jeeter’s explosive six-spot surge to #17 and Stiiizy’s systematic, month-over-month climb from #19 in June to the doorstep of the top ten at #11 showcase the power of high-impact retail merchandising and format-focused branding. Regional operators can no longer rely solely on local provenance; they must match national competitors in fulfillment consistency, eye-catching retail presentation, and store-level marketing support.Format Specialization and Value Positioning Unlock Immediate Market Entry
While breaking into the top 20 requires substantial scale, September’s rankings prove that buyers remain eager to onboard challenger brands that target specific consumer price points and product categories. The historic entry of Zips! directly at #32, the highest debut for any brand in recent months, highlights a clear market shift toward high-volume, value-driven flower offerings. Brands that enter the state with sharp pricing tiers, specialized format focus (such as bulk flower or infused pre-rolls), and distinct consumer appeal can bypass market crowding and achieve early retail velocity.
Sign up for a free trial today or book a personalized demo to start receiving real-time, actionable market signals for you and your entire team.