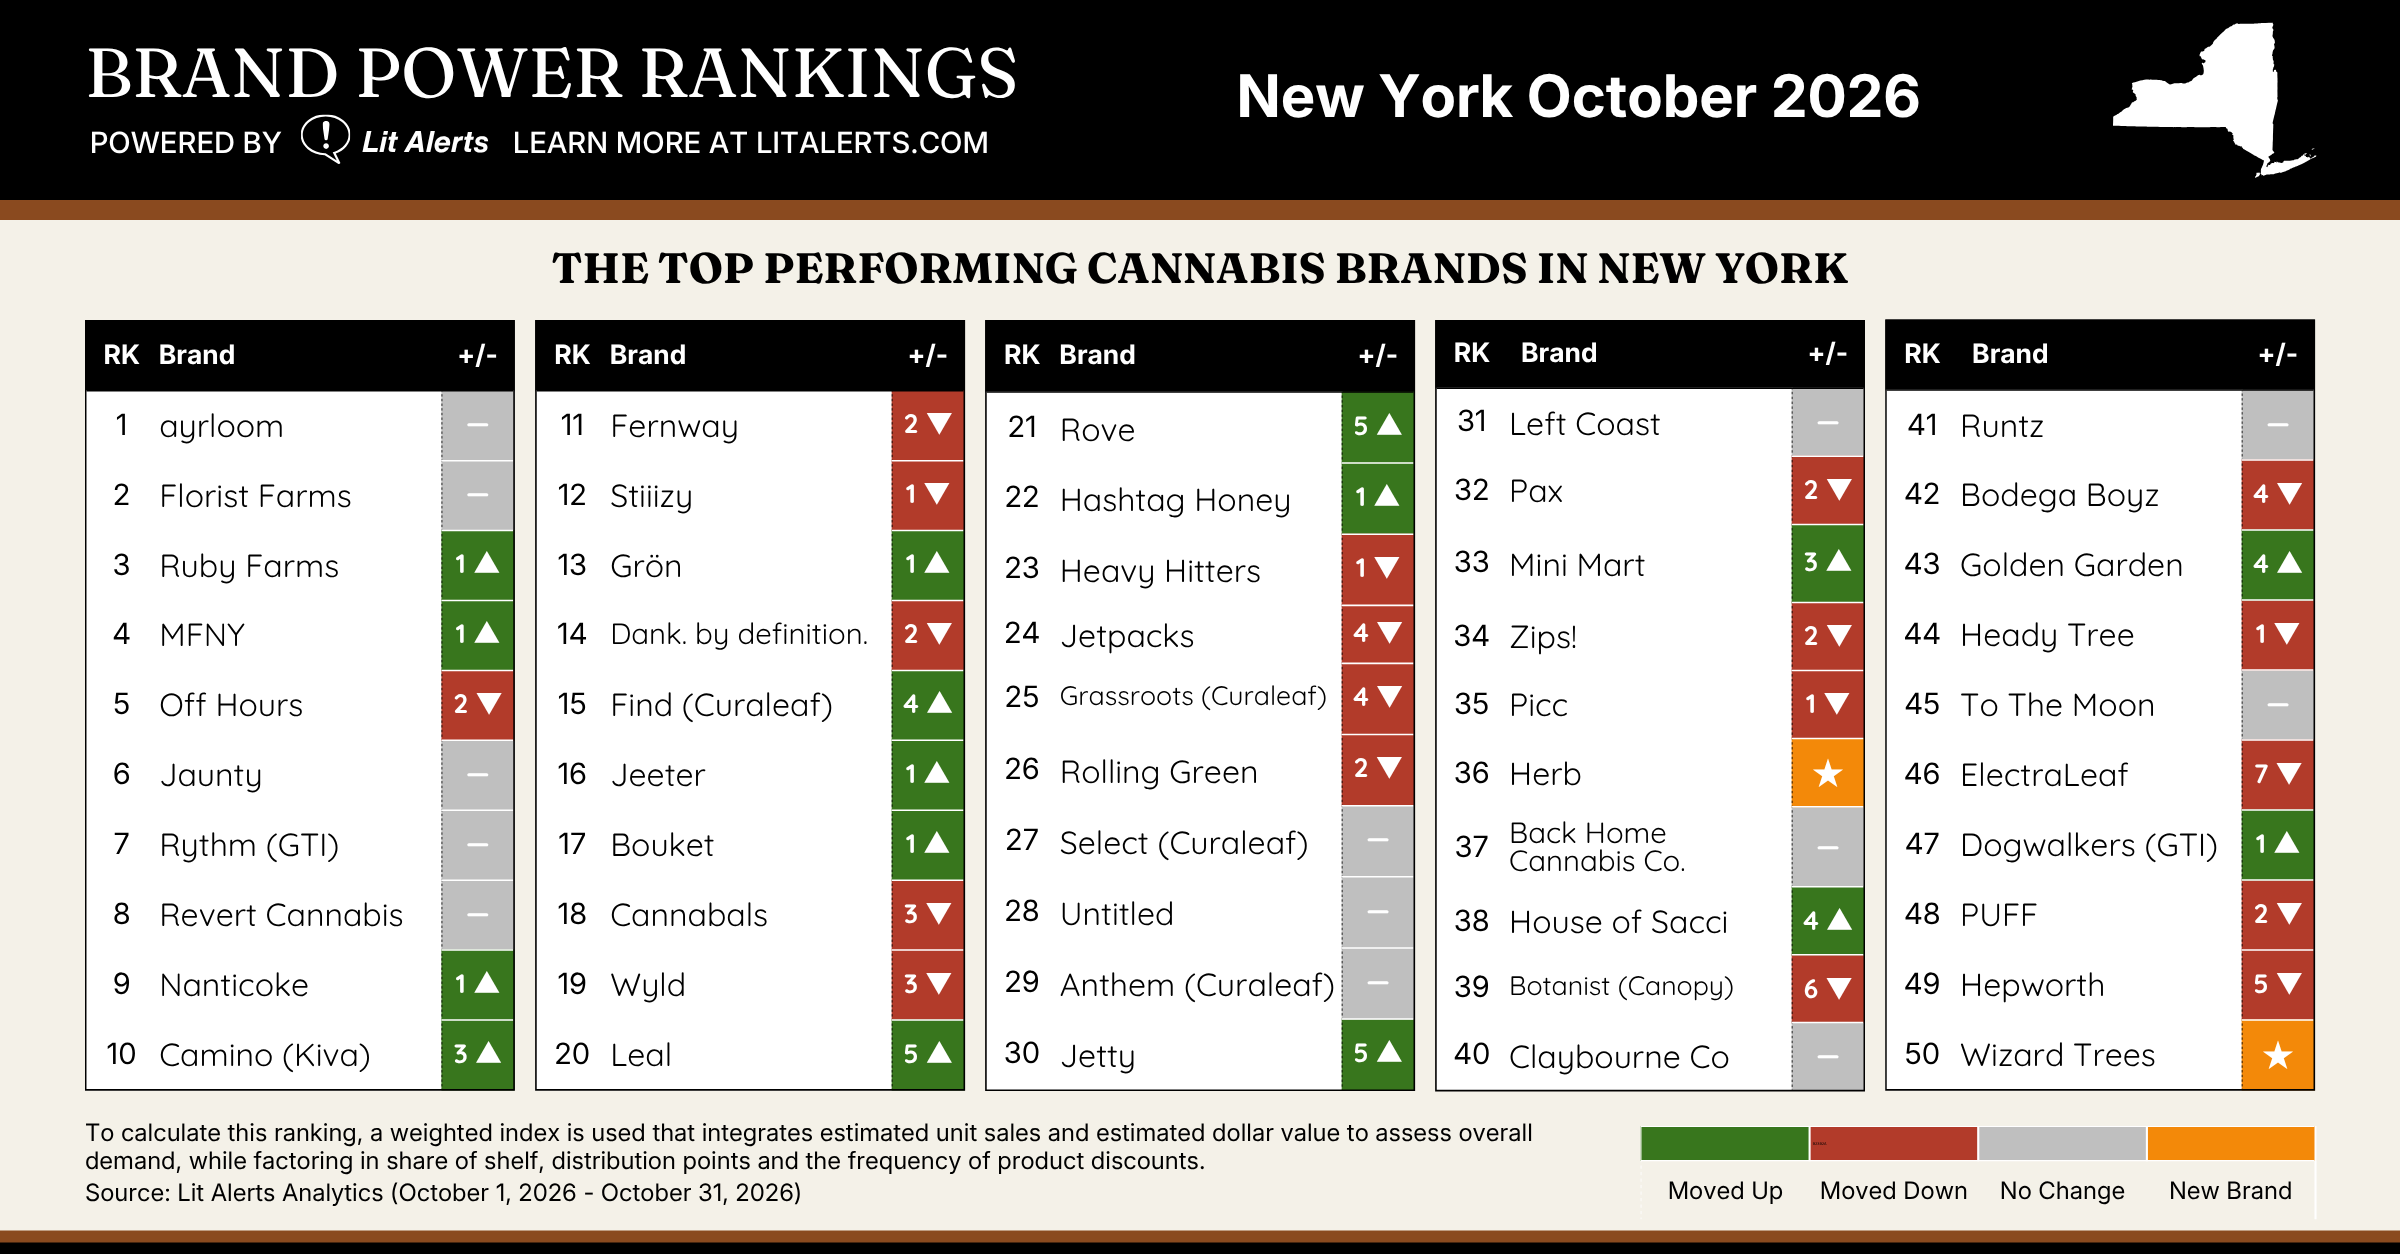
New York’s adult-use cannabis market delivered major structural surprises in October 2026, shattering months of top-tier gridlock and reinforcing the power of price-accessible offerings. For the first time in months, the untouchable top five experienced a positional shakeup, while the gateway to the top ten saw high-stakes friction between out-of-state juggernauts. Calculated through Lit Alerts’ weighted index, which synthesizes estimated unit volume, gross dollar sales, active dispensary distribution, shelf share, and discounting frequency, the October Brand Power Rankings demonstrate that retail menu real estate in the New York remains under active, ruthless curation. As the state moves deeper into the fall season, static inventory strategies are failing, and active daily monitoring is dictating brand survival.
The Top 5 Cracks as Value Brands Surge
Throughout the summer and early fall, New York’s podium appeared completely unshakeable. While September introduced heavy turbulence from #7 through #10, the top three positions had remained entirely frozen across June, July, August, and September. October broke that streak decisively.
While market leaders ayrloom (#1) and Florist Farms (#2) successfully defended their reign at the top, movement directly beneath them shattered the long-standing top-three podium. At the same time, consumer demand continued to tilt heavily toward bulk, value-driven offerings, welcoming another explosive brand debut into the Top 40 just weeks after last month’s bulk-flower shakeup.
The Top 5 Breaks: Ruby Farms and MFNY Rise as Off Hours Slips
The headline development at the peak of the chart is the first movement inside the top five in months. This level of disruption at the top indicates that buyers are actively reallocating prime shelf real estate based on real-time sales velocity.
Ruby Farms advanced +1 spot to seize the #3 position, reaching the podium after holding #5 in August and #4 in September. This methodical climb highlights the power of consistent flower availability and strong retail relationships.
MFNY climbed +1 position to capture #4, continuing an uninterrupted, multi-month ascent backed by premium concentrates and craft cured resin products. Their success proves that premium, craft-focused brands can still climb the ranks when backed by reliable distribution points.
Off Hours dropped -2 spots to #5, surrendering the #3 podium position it had maintained without interruption since June. While still a dominant force in the edible category, this slip demonstrates the fierce competition required to hold the podium.
Jaunty held perfectly flat at #6, stabilizing its position after dropping two spots in September.
This reshuffle at the summit signals that even legacy top-tier staples are susceptible to volume adjustments when craft favorites and disciplined multi-category producers ramp up their retail velocity.
Top 10 Tug-of-War: Camino Pushes In at Fernway's Expense
The lower half of the top ten witnessed an intense battle between national powerhouse brands, highlighting the fierce competition for premier edible and vape market share.
Camino (Kiva) vaulted +3 positions to claim #10, successfully penetrating New York’s elite top ten tier. Camino’s gummy line has steadily built momentum, advancing from #15 in August to #13 in September before securing a top-ten seat this month. Their targeted flavor profiles and consistent inventory fulfillment are clearly resonating with New York consumers.
Fernway slipped -2 spots to #11, falling just outside the top ten after briefly reclaiming #9 in September. The Massachusetts-based vape specialist continues to battle tightly for shelf space against expanding edible portfolios and hardware innovations.
Rythm (GTI) held firm at #7, protecting the major gains it achieved in September. This stability proves that Green Thumb Industries’ operational scale is translating to steady volume in New York.
Revert Cannabis maintained its ground at #8 for the second consecutive month, showing resilience amid heavy top-tier turbulence.
Nanticoke nudged up +1 position to #9, rebounding after dropping two spots in September.
The swap between Camino and Fernway illustrates the zero-sum nature of New York’s top tier: entry into the top ten almost inevitably requires displacing an established market leader. Operators cannot afford to walk into morning meetings with surprise stock-outs when margins are this tight.
National Giants Cool Off: Stiiizy and Jeeter Hit the Top 10 Wall
Over the late summer, national brands mounted aggressive, multi-spot surges up the leaderboard. However, October data reveals that both Stiiizy and Jeeter have finally cooled off, demonstrating that breaking into the top 10 is proving far more difficult than storming through the mid-tier.
Stiiizy slipped -1 position to #12. After climbing from #19 in June to #11 in September, Stiiizy’s charge met immediate resistance right on the doorstep of the top ten. Crossing the top-ten threshold requires unseating deeply entrenched regional flower and edible brands.
Jeeter managed a modest +1 gain to #16. While still advancing, this single-spot nudge represents a notable deceleration after its explosive six-spot leap in September.
Both brands have established immense statewide consumer demand and robust retail distribution, but displacing entrenched regional champions at the top requires sustained replenishment that goes beyond introductory brand buzz. This is where real-time market data and analytics become the differentiator between stalling out at #12 and breaking into the top 5.
Mid-Tier Churn & Notable Moves
Beyond the upper echelon, October featured widespread movement across mid-tier and developing brands, highlighting how quickly fortunes can change for operators lacking automated inventory oversight:
Rove surged +5 spots to #21, staging a powerful recovery after slipping five spots in September.
Leal jumped +5 positions to reach #20, breaking into the top twenty with authority and proving the efficacy of their recent retail pushes.
Jetty advanced +5 spots to #30, reclaiming top-30 placement after navigating a highly competitive vape and concentrate landscape.
Find (Curaleaf) rallied +4 positions to #15, driving strong gains for Curaleaf’s value-oriented flower tier and reinforcing the broader market trend toward accessible pricing.
House of Sacci (+4 to #38) and Golden Garden (+4 to #43) both recorded healthy climbs in the lower half of the chart, showcasing how newer entrants can steadily build momentum.
Dank. by definition. dropped another -2 spots to #14, continuing a steady retreat from its #9 position in August and #12 in September.
The Rise of Value: Herb's All-Star Debut Follows Zips!
Consumer demand for high-volume, cost-effective flower continues to reshape retail inventories, paving the way for another standout debut. As the New York consumer base matures, daily consumers are actively hunting for bulk options that maximize value per gram.
Herb made an all-star debut, entering the rankings directly at #36.
This debut arrives exactly one month after bulk-flower challenger Zips! entered the charts at #32 in September.
Zips! proved its holding power this month, staying well within the core rankings at #34 (-2), demonstrating that its initial September surge was a reflection of sustained consumer appetite for bulk formats.
The back-to-back high debuts of Zips! and Herb underscore an unmistakable market reality: retail dispensaries and consumers are prioritizing accessible, value-driven flower options to drive basket sizes and volume as market compression continues. For wholesale teams, this signals a critical need to monitor active dispensary distribution points daily to see exactly where these value brands are eating into premium flower shelf space.
Takeaways for New York Cannabis Brands
Analyzing the brand power trajectory across the transition from summer into late fall reveals critical strategic shifts defining the New York’s adult-use landscape. For operators, wholesale teams, and brand strategists navigating New York’s expanding retail ecosystem, three core takeaways define current market dynamics:
The Top 10 Barrier Is a High-Velocity Defense. While national giants like Stiiizy and Jeeter have captured significant consumer mindshare, their momentum plateaued just outside the top 10. The established volume of New York’s incumbent leaders means that storming the gates requires more than brand recognition. It demands constant retail replenishment and localized budtender support. Regional champions are holding the line because they do not miss delivery windows.
Value-Tier Flower Is Reshaping Retailer Menus. The immediate traction of Herb (#36) following closely behind Zips! (#34) highlights that daily consumers are actively shopping for value per gram. Brands lacking an accessible pricing tier or high-volume SKU strategy risk losing share to focused value competitors. As buyers actively reallocate shelf real estate toward bulk options, premium and mid-tier brands find ways to ensure loyal customers can always find their specific SKUs amid the shifting menu landscapes.
Out-of-State Edible Portfolios Command Market Share. Camino’s breakthrough into the top 10 demonstrates that multi-market edible brands with broad flavor varieties, consistent dosing, and brand consistency can unseat the incumbents in the category. Diversification and shelf longevity remain paramount to holding long-term position in the New York.
Sign up for a free trial today or book a personalized demo to start receiving real-time, actionable market signals for you and your entire team.