Following last month’s launch of our expanded multi-category Retail Price Index, we are back with the November 2026 New York Update. Compiling six months of real-time retail menu data collected from May 1, 2026, through October 31, 2026, across New York State, this report isolates average retail shelf prices, unit economics, and six-month price trajectories across both inhalable and ingestible categories. As fall harvest inventory hits retail shelves and wholesale competition intensifies, our latest dataset reveals relentless downward price pressure across inhalables, persistent structural pricing inversions, and sharp divergence across ingestible formats.
The New York Category Retail Price Index Breakdown
Downward Trends, Anomalies, and Pricing Inversions in New York
While every SKU in the Inhalables Index declined in average retail price between May and October 2026, the rate of compression, and the relationship between package size and shelf price—, gory.
The Bulk Flower Volume Curve Deepens
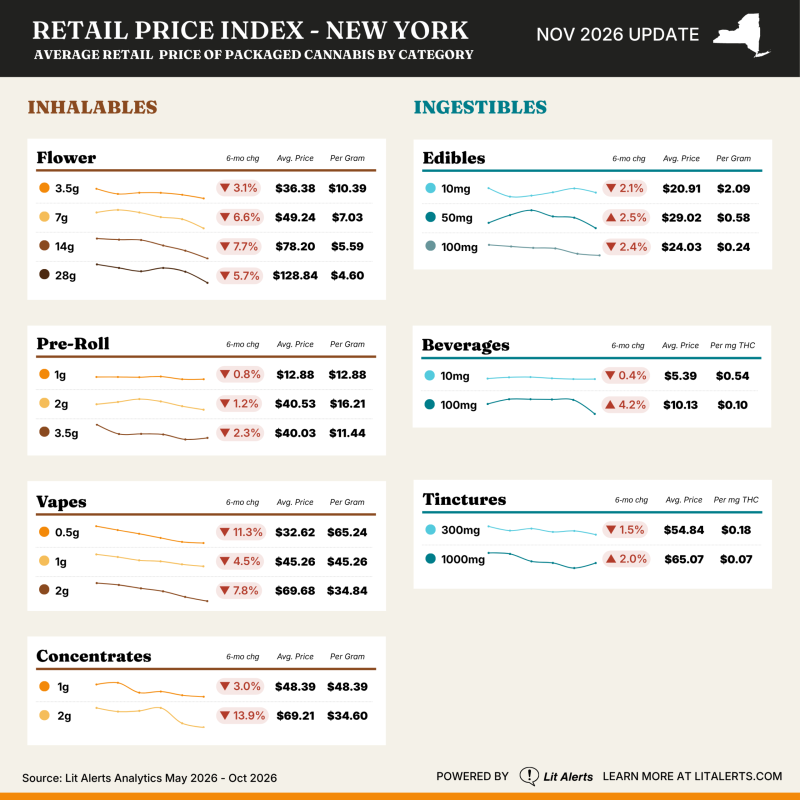
In the flower aisle, scaling up package size delivers substantial unit-cost savings for consumers while accelerating volume velocity for brands:
3.5g Eighths: $36.38 average ($10.39 per gram)
7g Quarters: $49.24 average ($7.03 per gram)
14g Half-Ounces: $78.20 average ($5.59 per gram)
28g Ounces: $128.84 average ($4.60 per gram)
Purchasing a full 28-gram ounce delivers an immediate 55.7% per-gram discount compared to buying a standard 3.5-gram eighth—widening from the 54.7% discount recorded in October’s report. Unit volume data confirms that New York shoppers are migrating toward bulk formats. Between May and October, standard 3.5g eighth sales grew +11.8%, whereas 14g half-ounce volume surged +26.8% and 28g ounce volume climbed +23.0%. As fall harvest biomass enters the supply chain, cultivators and value-tier challengers are aggressively pricing half-ounce (-7.7%) and quarter-ounce (-6.6%) bags to move volume.
The Pre-Roll Inversion Anomaly
The pre-roll category continues to display one of the sharpest structural pricing inversions on New York dispensary shelves:
2.5g Pre-Roll Package: Average price of $40.53 ($16.21 per gram)
3.5g Pre-Roll Package: Average price of $40.03 ($11.44 per gram)
Even though a 3.5g multi-pack contains a full gram more cannabis than a 2.5g pack, the 2.5g configuration commands a higher average retail price—and a 41.7% higher cost per gram. This inversion stems from sub-category mix and product format. The 2.5g tier is populated largely by infused multi-packs (such as 5-packs of 0.5g joints enhanced with liquid diamonds, distillate, or kief), whereas 3.5g packs consist primarily of uninfused commodity flower multi-packs.
The Edibles Dosage Disconnect
A parallel pricing inversion persists in the ingestibles aisle, where mid-tier dosage packs cost significantly more per unit than full-potency 100mg packages:
50mg Edibles: Average price of $29.02 ($0.58 per mg THC)
100mg Edibles: Average price of $24.03 ($0.24 per mg THC)
Consumers purchasing a 100mg edible package pay $4.99 less out of pocket, and receive a 58.6% discount per milligram of THC, compared to shoppers buying a 50mg pack. Standard 100mg gummies operate as high-velocity staples, moving +11.6% more units in Oct compared to May while compressing -2.4% over the same time period. Conversely, the 50mg tier represents a niche segment and is down -8.8% since May. This weight class is dominated by ratio-specific formulations, minor cannabinoids like CBN and CBG, and artisanal confections that sit outside mainstream gummy price wars. Meanwhile, 10mg edibles averaged $20.91 ($2.09 per mg THC), reflecting specialty multipacks or boutique single-unit formats whose volume slipped -8.6% over six months.
The Islands of Price Stability: 1g Pre-Rolls and 10mg Beverages
While most categories experienced steady downward price drift, two impulse SKUs maintained remarkable price rigidity from May through October:
1g Single Pre-Rolls: Operating as the checkout counter staple across New York dispensaries, 1g singles moved from $12.98 in May to $12.88 in October, a minimal -0.8% shift (-$0.10) across six months, while unit volume jumped +24.8%.
10mg Single-Serve Beverages: Low-dose infused beverages held essentially flat, moving just -$0.02 (-0.4%) from $5.41 in May to $5.39 ($0.54 per mg THC) in October, while growing unit sales +22.1%.
New York Historical Perspectives: The Price Compression Leaders
Examining the six-month dataset from May 1, 2026, through October 31, 2026, pinpoints where margin compression is hitting New York operators hardest:
Steepest Percentage & Dollar Drop — 2g Concentrates (-13.9%): In both absolute dollar terms and percentage contraction, 2g Concentrates recorded the steepest six-month decline in New York, dropping from $80.42 ($40.21/g) in May to $69.21 ($34.60/g) in October (-$11.21 per unit). After holding steady around $80 through August, 2g jars broke downward in September ($71.58) and continued sliding in October. Unlike distressed clearance, this repricing unlocked massive demand: monthly unit volume surged +85.0%, as a 28.5% per-gram discount over 1g jars ($48.39) converted heavy consumers to multi-gram formats.
Persistent Hardware Erosion — 0.5g Vape Cartridges (-11.3%): While 2g concentrates repriced to capture volume, 0.5g Vape Cartridges suffered relentless month-over-month price erosion accompanied by shrinking demand, sliding from $36.78 ($73.56/g) in May to $32.62 ($65.24/g) in October (-$4.16 per unit). At $65.24/g, half-gram carts remain far costlier per unit of oil than 1g carts ($45.26/g, down -4.5%) and 2g all-in-one vapes ($34.84/g, down -7.8%). Consequently, 0.5g vape volume fell -21.3%, while 1g volume rose +25.5% and 2g volume jumped +33.0%.
Strategic Takeaways for New York Operators
Navigating a market where bulk flower discounts exceed 55% and multi-gram concentrates drop nearly 14% in six months requires real-time menu intelligence rather than static spreadsheet guesses:
Align Inventory With the Bulk & High-Capacity Shift: Consumers are voting with their wallets for lower per-gram and per-milligram economics across flower (14g/28g), vapes (1g/2g), concentrates (2g), and high-dose beverages (100mg surged +34.8% in volume at $10.13 per unit). Brands over-indexed on 0.5g vapes or small-format flower without an accessible bulk tier risk losing shelf allocation.
Protect Margin on Impulse Staples: Single 1g pre-rolls ($12.88) and 10mg beverages ($5.39) prove that disciplined CPG pricing can hold firm even during broader market compression. Operators do not need to race to the bottom on checkout-counter staples when velocity is already climbing over 20%.
For more pricing info and comprehensive market analytics, schedule a demo or sign up for a 30-day free trial to Lit Alerts today.