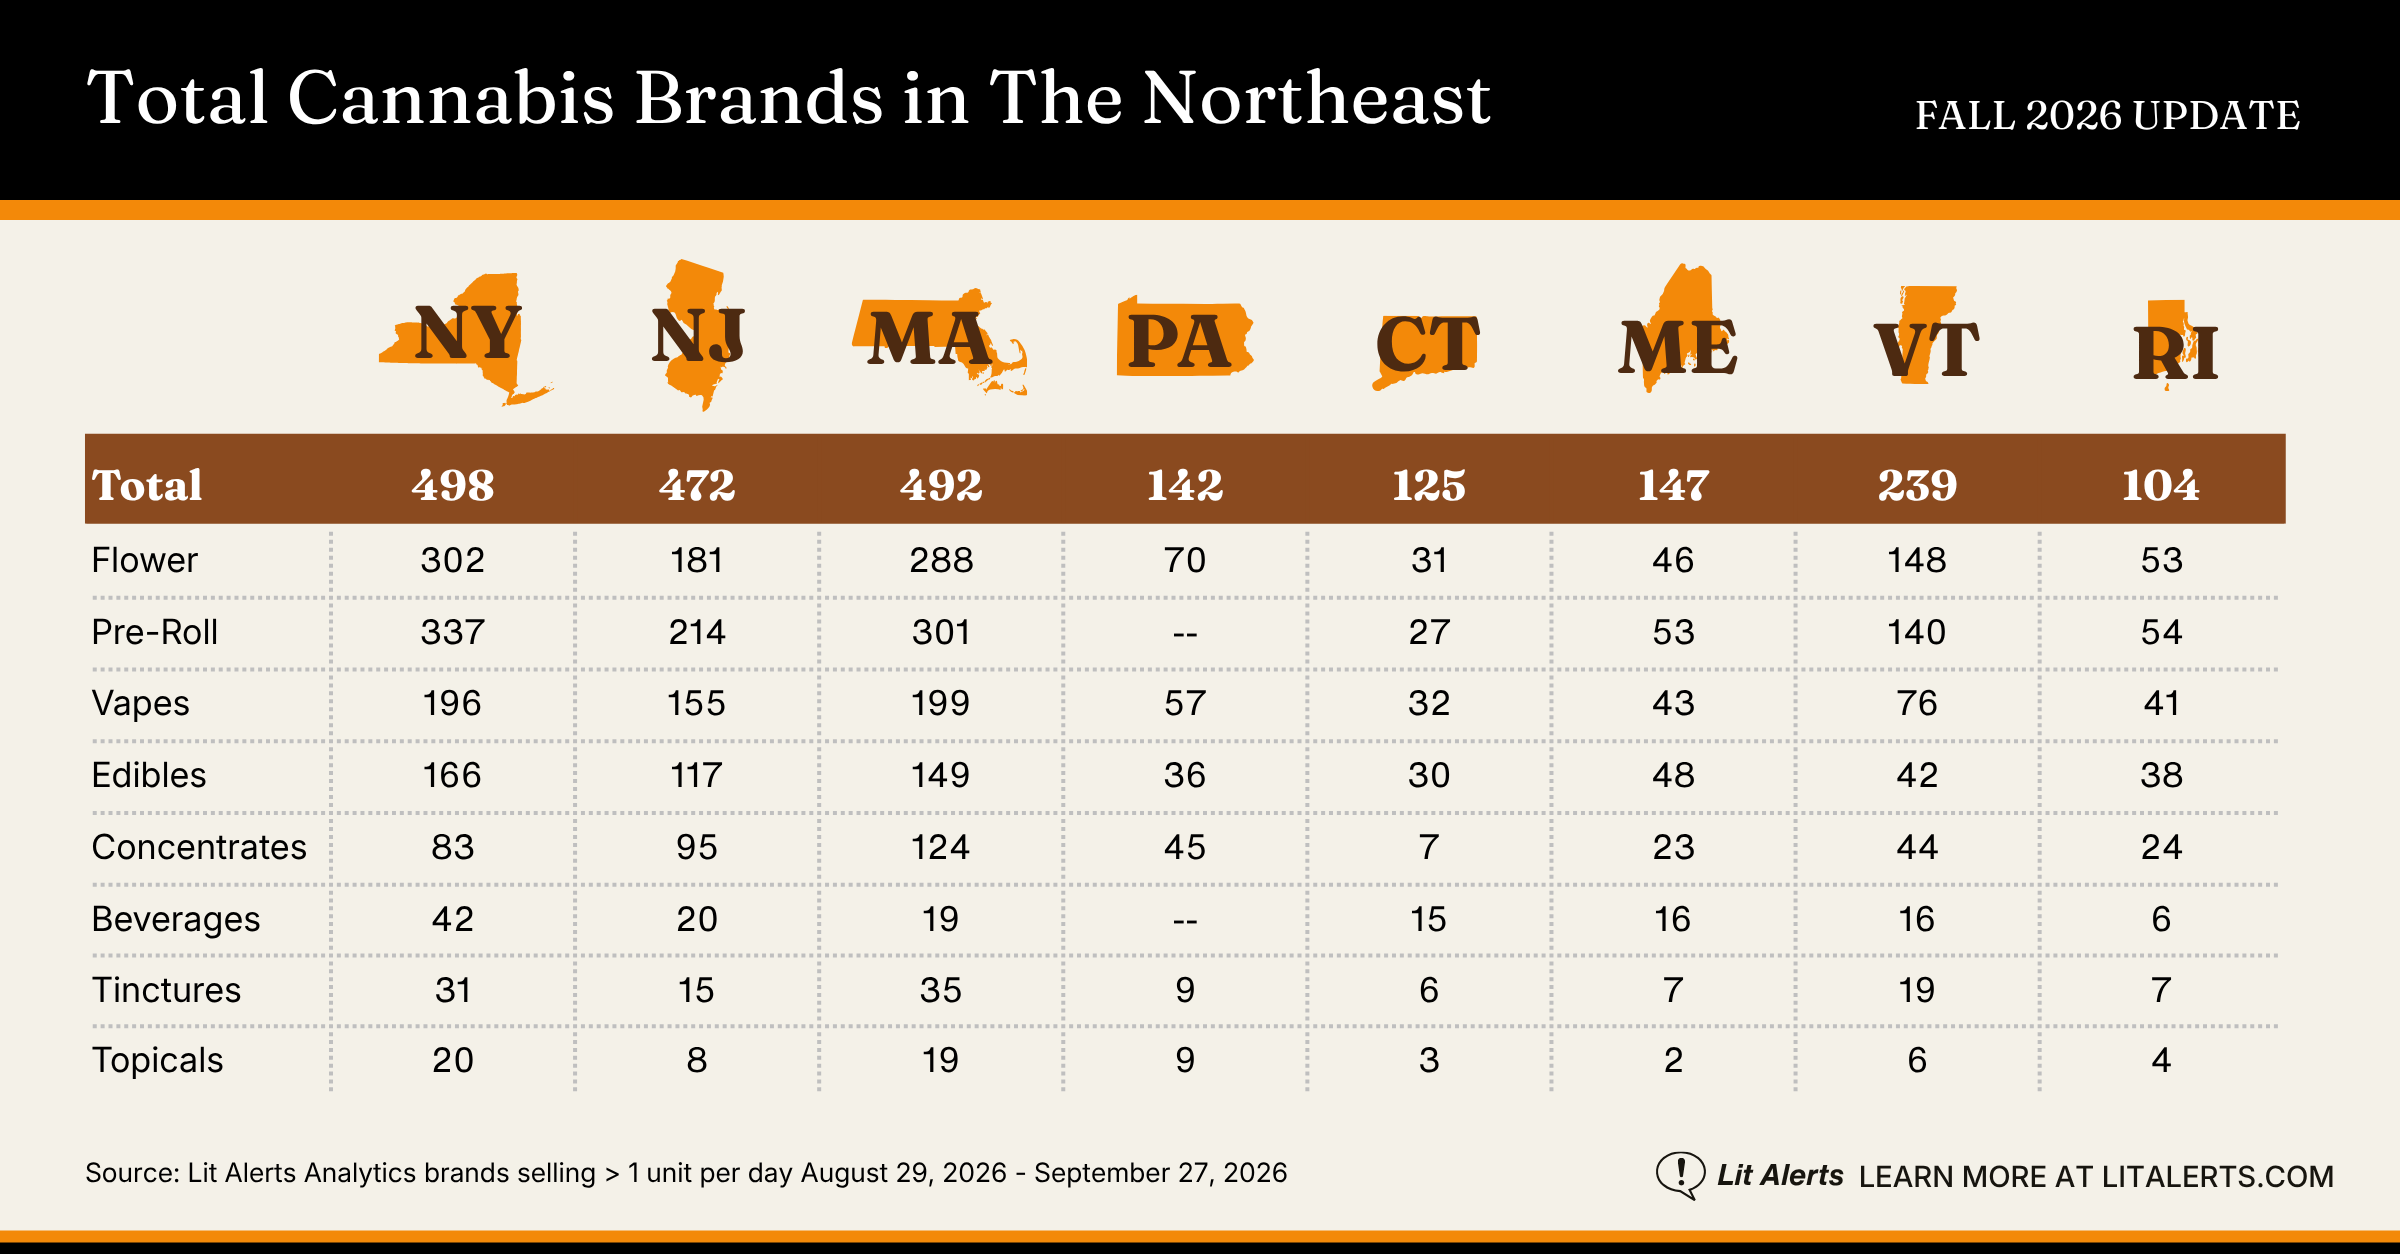
The Northeast cannabis landscape has transformed into one of the most competitive, fast-moving regional markets in the country. According to Lit Alerts market analytics tracking active brands selling at least one unit per day from late August through late September 2026, market saturation and product distribution vary significantly across state lines.
Whether you are a retail buyer trying to curate a high-performing menu or a brand executive planning your next multi-state expansion, understanding where active shelf presence stands is critical.
A high brand count doesn’t always equal market dominance. Comparing top-line figures without market context misses the real story. When you cross-reference active brand counts against market age, state population, population density, and licensing structure, a far more nuanced picture of regional competition emerges.
Market Dynamics: Maturity, Population, and Regulatory Caps
Massachusetts vs. New York (Market Maturity vs. Sheer Volume): New York leads the region with 498 total active brands. However, with a population of roughly 20 million and adult-use sales starting in late 2022, NY’s market is still absorbing brand entry. In contrast, Massachusetts (~7.1 million residents) launched retail sales in 2018 and supports nearly the exact same volume at 492 active brands. Per capita, Massachusetts features nearly triple the brand density of New York, signaling a hyper-mature market where shelf-space competition is at a fever pitch.
New Jersey vs. Connecticut (High Density vs. Regulatory Bottlenecks): New Jersey is the most densely populated state in the nation (~1,300 residents per square mile) and hosts 472 active brands serving 9.5 million residents in a compact footprint. This creates intense geographic competition among retail buyers and sales teams. Meanwhile, Connecticut shares high population density (#5 nationwide) and 3.7 million residents, but strict state licensing caps have held its active market to just 125 brands.
Vermont (The Craft Per-Capita Powerhouse): Vermont’s population sits at just ~647,000 residents, yet the state boasts 239 active brands. Micro-licensing laws and a strong local craft ethos give Vermont roughly 37 active brands per 100,000 residents—by far the highest per-capita brand diversity in the Northeast.
Pennsylvania (The Medical Ceiling): Despite having 13 million residents, Pennsylvania trails with 142 active brands. Its medical-only regulatory framework throttles product diversification, completely excluding standard adult-use pre-rolls and commercial beverages while capping overall brand expansion.
Category Trends: Pre-Rolls Surge as Specialty Form Factors Hold Whitespace
1. Pre-Rolls and Flower Drive Menu Volume
In every adult-use state, Flower and Pre-Rolls represent the core of active brand diversity. New York leads with 337 Pre-Roll brands and 302 Flower brands, closely mirrored by Massachusetts with 301 Pre-Roll brands and 288 Flower brands. Even in Vermont, Flower (148 brands) and Pre-Rolls (140 brands) represent over half of the market’s total brand count.
2. Regulatory & Market Variations
Pennsylvania’s active brand lineup reflects its medical status, with activity concentrated in Flower (70 brands), Vapes (57 brands), Concentrates (45 brands), and Edibles (36 brands). Categories like pre-rolls and infused beverages remain absent due to state regulations.
3. Whitespace in Beverages, Tinctures, and Topicals
While core categories are crowded, specialty form factors present clear expansion opportunities:
Beverages: Outside of NY (42 brands), beverage brand counts hover between 15 and 20 across NJ, MA, VT, ME, and CT.
Topicals & Tinctures: Topicals remain the smallest category in every state, topping out at 20 brands in NY and remaining in single digits across most other markets.
Stop Guessing What’s on the Shelf
When hundreds of brands compete across disparate state markets, tracking dynamic shelf presence and velocity manually is a losing battle. Missing stock-out signals or failing to spot distribution gaps before your morning stand-up means leaving revenue on the table.
With Lit Alerts, brand strategy teams, MSOs, and retail buyers get automated data intelligence delivered directly to their workflow. Whether you need 6:00 AM daily inventory snapshot emails, self-updating web store locators, or REST APIs for custom CRMs, Lit Alerts gives you the competitive edge.
Sign up for a free trial today or book a personalized demo to start receiving real-time, actionable market signals for you and your entire team.